Look Ahead, Not Around
A broader, healthier rally across global equities started to emerge over the June quarter.
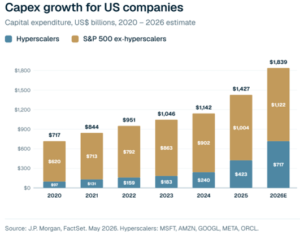
The story is no longer just AI. It’s where the next wave of investment is flowing, creating opportunities well beyond the technology sector.
Geopolitical shocks and central bank uncertainty aren’t going away. Markets may react in the short term, but they eventually look ahead. That can feel uncomfortable for investors, but it’s often when the biggest opportunities emerge.
In our latest Quarterly Investment Report, we explore what this shift means for portfolios in the second half of 2026.
Here’s what we cover:
- AI investment is becoming a key driver of economic growth, expanding beyond technology into power, defence and manufacturing.
- The global rally is broadening, with earnings replacing enthusiasm as the key driver of returns.
- Australia’s growth outlook is softening, with higher rates and persistent inflation weighing on activity.
- Housing momentum is slowing as affordability pressures and higher borrowing costs weigh on demand.
We hope you find the report valuable and look forward to staying connected throughout the second half of 2026.
Warm regards,
Mackay Private Wealth
General Advice Warning: Any comments in this communication do not consider your objectives, financial situation or needs. Before acting on any general advice, consider whether it is appropriate for you.